


Many commercial cleaning firms overlook how asset depreciation eats into their bottom line until they attempt to sell used hardware. Distinguishing between high-tech electronic assets and traditional mechanical tools helps owners project actual cash returns and better manage their secondary market listings.
We break down the 2026 valuation frameworks for commercial vacuums, comparing the liquidation floors for corded and cordless models. This guide explores why copper-wound motors retain a scrap value of up to $4.50 per pound while battery-powered units often face a 50% price penalty within just three years of service.
The Depreciation Curve: Electronics vs. Tools
تفقد الأجهزة الإلكترونية 30–70% من قيمتها خلال العام الأول نظراً للتقادم التكنولوجي السريع، بينما تتبع الأدوات التقليدية معدل إهلاك أكثر استقراراً يبلغ 16% سنوياً. يتطلب إدارة هذه الأصول منهجيات محاسبية متميزة—مثل الرصيد المتناقص للتقنية والخط المستقيم للأدوات—لتوقع عوائد إعادة البيع بدقة في عام 2026.
التقادم التكنولوجي وخسارة القيمة المبكرة
تفقد الحواسيب المحمولة والأجهزة الإلكترونية الذكية 30–70% من سعر شرائها الأولي خلال الأشهر الاثني عشر الأولى. ينشأ هذا الانخفاض الحاد من التطورات السريعة في قوة المعالجة وكفاءة البطاريات، مما يجعل الموديلات الأقدم غير وظيفية وإن كانت بحالة مادية مثالية. غالباً ما تشهد الأجهزة المحمولة مثل وحدات تحكم المكنسات الكهربائية والثلاجات الذكية للسيارات انخفاضاً في القيمة يبلغ 240 جنيهاً استرلينياً على استثمار أولي مقداره 600 جنيهاً بحلول العام الثاني. وبينما تُعد البلى المادي عاملاً مؤثراً، فإن تشبع السوق بالإصدارات الأحدث والأكثر كفاءة لعام 2026 يمارس أقوى ضغوط هبوطية على أسعار إعادة البيع.
معدلات الإهلاك المقارنة والمنهجيات المحاسبية
تتبع الأدوات الميكانيكية مساراً أكثر قابلية للتنبؤ، حيث تحافظ على معدل إهلاك سنوي بنسبة 16% طوال فترة عائد استخدام قياسية تبلغ 8 سنوات. يستخدم المديرون الماليون طريقة الرصيد المتناقص لمتابعة تضعضع التكنولوجيا الفائقة، بتطبيق معدل 40% على القيمة الدفترية المتبقية كل عام لتعكس تسعير السوق الفعلي. تحافظ الحواسيب المكتبية والمعدات الثابتة على معدل إهلاك رسمي أقصى يبلغ 26% سنوياً على مدى فترة تتراوح بين 3 إلى 10 سنوات. يساعد تطبيق طريقة الرصيد المزدوج المتناقص المؤسسات على مواءمة كتبها المالية مع سوق عام 2026، حيث تضاعف المعدل الخط المستقيم البالغ 20% ليصبح 40% للأصول التكنولوجية.

The “Used Battery” Stigma in the Second-Hand Market
غالباً ما يعاقب المشترون الأصول القديمة التي تعمل بالبطاريات بانخفاض قيمتها بنسبة 50% على مدار ثلاث سنوات، رغم أن البيانات الفنية تظهر تدهوراً سنوياً بنسبة 1-2% فقط. يستمر هذا الوصم بسبب نقص معايير التشخيص الموحدة، مما يجعل البطارية ‘صندوقاً أسود’ عالي المخاطر بالنسبة للمت參與ين في سوق مستعمل.
عدم تناسق المعلومات وفجوات تقييم الأصول
تعتمد الأسواق التقليدية للسيارات على تسعير يعتمد على عدادات المسافات امتد لعصر واحد لقياس القيمة المتبقية. تفتقر أنظمة أيون الليثيوم حالياً إلى هذه المعايير التاريخية الراسخة، مما يترك المشترين دون مقياس موثوق للصحة طويلة المدى. نظراً لأن حزمة البطارية يشكل غالبية التكلفة الإجمالية للأصل، فإن أي غموض يتعلق بحالته يترجم إلى عقوبة سعرية حادة. تُظهر الإحصاءات أن الوحدات الكهربائية البالغ عمرها 3 سنوات غالباً ما تفقد أكثر من نصف سعرها الأصلي، بينما تحافظ البدائل الميكانيكية على حوالي 61% من قيمتها. ينشأ هذا التباين من فجوة معلوماتية وليس من تآكل مادي فعلي أو عطل ميكانيكي.
مقاييس التدهور الفني وتعافي السوق
Technical evidence suggests that post-2016 battery systems are far more durable than consumer sentiment implies. Most units experience only 1% to 2% annual capacity loss, and only 1% of EVs produced after 2016 have required a full battery replacement. Market participants are closing the trust gap by adopting smart diagnostics and clear warranty transfer protocols. Certified units move through the secondary market six times faster than those without documented health reports. The projected $4.2 billion second-life battery market by 2035 further stabilizes residual values by ensuring that even aged units remain valuable for grid storage and recycling applications.
Refurbishment Potential: Corded Resale Value
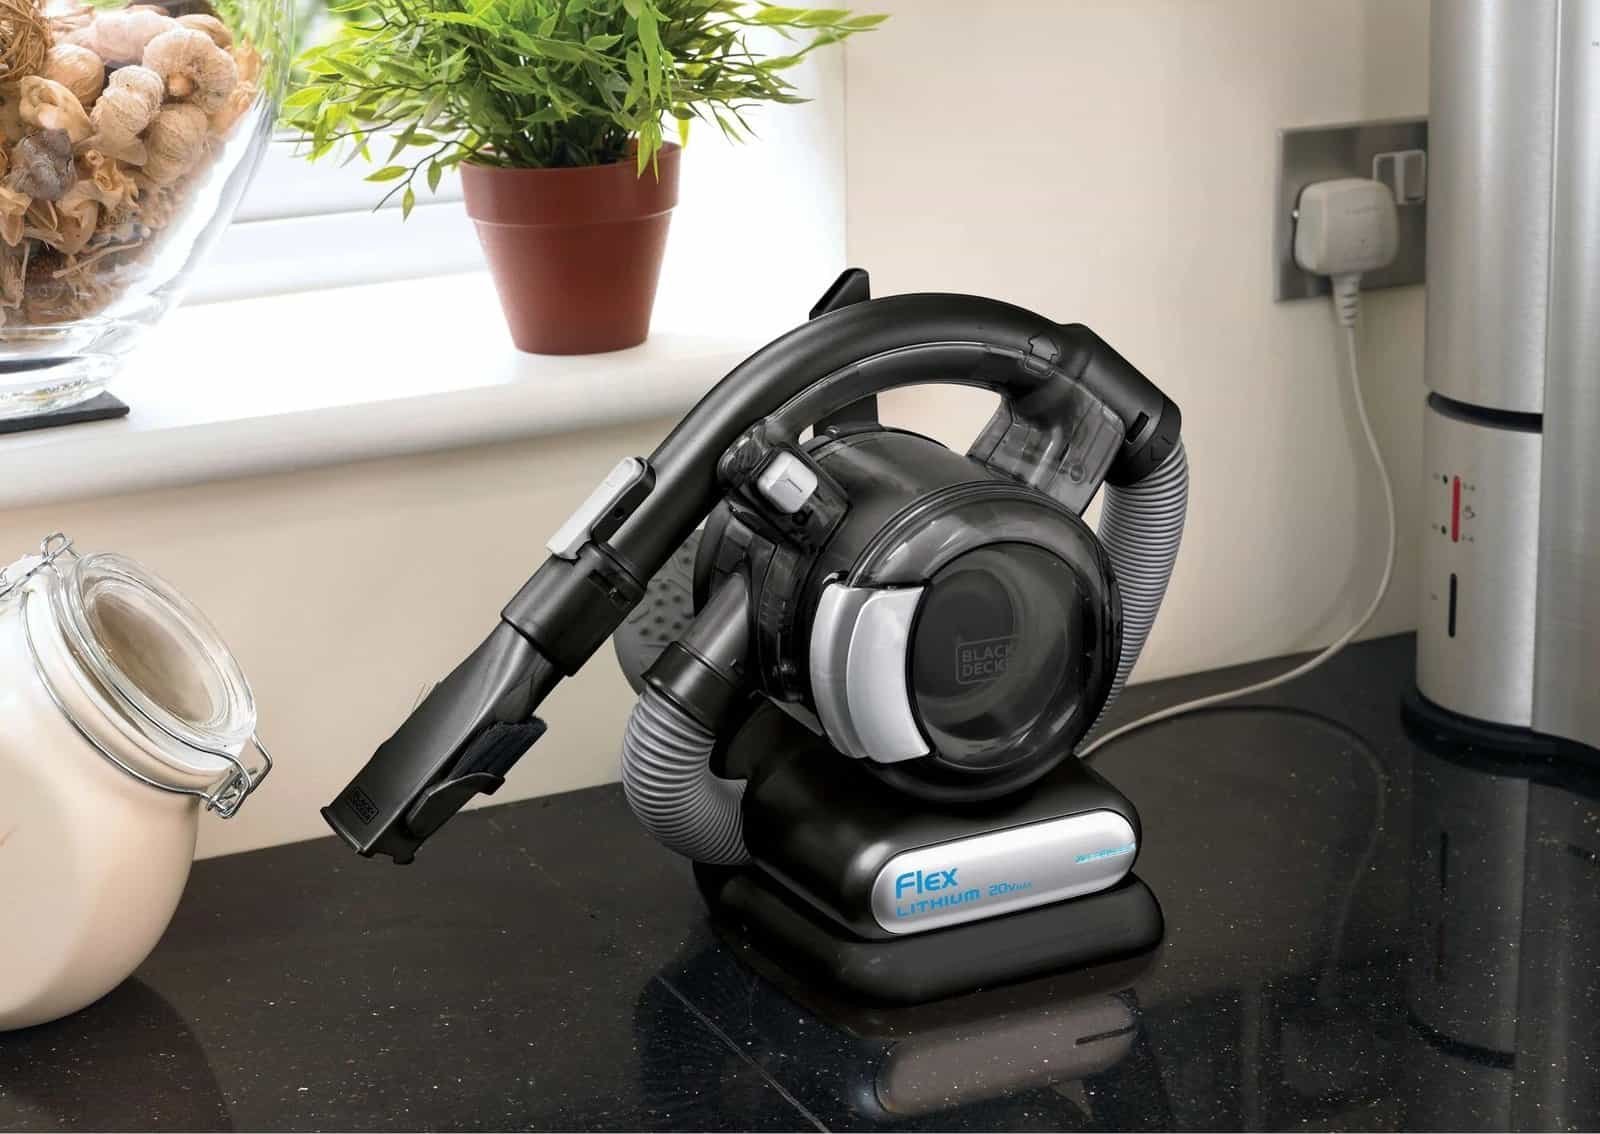
Corded equipment consistently maintains higher resale value than cordless alternatives in 2026, often retaining 70% of its original list price. This stability results from the durability of copper motors and strict adherence to NEC 2020 reconditioning standards, which ensure safety and performance without the risks of battery degradation.
Value Retention and the Corded Advantage
Secondary market buyers prioritize corded tools to avoid the stigma associated with used batteries and the unpredictable costs of cell replacement. Because corded motors lack volatile chemical components, they offer a predictable service life that appeals to B2B liquidation cycles. Refurbished industrial electrical gear offers 40-60% savings compared to new units, which sustains a high demand for used equipment in the secondary market.
Valuation models for 2026 typically set a baseline of 70% of the original list price for name-brand corded tools accompanied by documented maintenance logs. This high retention rate stems from the inherent longevity of copper-wound motors and the absence of proprietary battery platforms that often lead to obsolescence. Asset managers rely on these stable valuations to justify the procurement of corded equipment for long-term industrial projects.
Regulatory Standards for Reconditioned Equipment
NEC 2020 sections 240.88 and 408.8(B) establish the legal framework for reconditioning circuit breakers and switchgear. These regulations allow components like molded-case circuit breakers and medium-voltage power circuit breakers to be restored to operating condition while maintaining their market value. Field-labeling for reconditioned switchboards permits commercial entities to liquidate assets safely, provided they follow local electrical codes and performance testing requirements.
Compliance with the NEMA CS 100-2020 standard ensures that reconditioned assets meet rigorous safety and labeling criteria. This standard provides the prescriptive actions necessary to verify that used equipment performs as intended after refurbishment. Restrictions under NEC 240.88(B)(1) prohibit the reconditioning of electronic trip units on low-voltage breakers, which sets a hard ceiling on the resale potential of more complex electronic components compared to standard electromechanical corded machinery.
Scale Your Brand with High-Performance Vacuum Manufacturing

Liquidation Value for Commercial Cleaning Companies
Liquidation value represents the estimated net cash a cleaning business generates by selling assets and settling debts in a short timeframe. In 2026, this value serves as a safety floor, typically recovery 50% of inventory book value and 70% of accounts receivable, while specialized equipment fluctuates based on secondary market demand.
Valuation Frameworks and Asset Recovery Floors
Calculating a cleaning company’s base value requires a clear distinction between orderly and forced liquidation. An orderly liquidation assumes the business has several months to identify buyers for specialized equipment and vehicles, which generally secures higher recovery rates. Forced liquidation assumes a rapid exit, often at auction, where assets sell quickly at a steep discount to their book value.
Standard market assessments in 2026 weigh the relationship between EBITDA multiples and the hard asset floor. While healthy operations might trade at 3x to 5x EBITDA, the liquidation value establishes the absolute minimum price for an exit. When a business experiences financial distress, this floor ensures that creditors and owners understand the cash-in-hand reality of the company’s tangible assets.
Owner dependence and customer concentration significantly influence the final recovery. If a cleaning service relies heavily on the owner’s personal relationships or a single large contract, the intangible value disappears during a sale. In these scenarios, the valuation shifts focus entirely to physical inventory and the strength of the accounts receivable aging report.
Technical Recovery Benchmarks for Equipment and Receivables
Inventory recovery rates for cleaning supplies and chemicals average approximately 50 cents on the dollar. This discount reflects the logistical challenges of transporting bulk chemicals and the limited demand for partially used stock. High-quality, sealed concentrates from reputable brands maintain the best recovery percentages in the secondary market.
Liquidation discounting for accounts receivable often reaches 30%, meaning buyers pay roughly 70% of the book value. This reduction accounts for the increased difficulty of collecting payments once a service provider ceases operations. Clients sometimes delay final payments during business transitions, making a verifiable and current AR report vital for a successful asset sale.
Resale performance for specialized hardware like HEPA-filtered vacuums and industrial floor scrubbers remains steady in the second-hand facility management market. These items hold value better than generic janitorial tools because of their high replacement costs and المواصفات الفنية. Maintaining detailed maintenance logs for this equipment helps support higher recovery values during the liquidation process.
Tax Implications: Capital Asset Depreciation Schedules
Businesses recover the cost of automotive accessories like portable fridges and شواحن السيارات الكهربائية through the Modified Accelerated Cost Recovery System (MACRS). For the 2026 tax year, these assets typically fall under the 5-year property class, allowing owners to apply Section 179 deductions and bonus depreciation to front-load expenses and lower the adjusted basis before liquidation.
| Asset Category | Recovery Period | 2026 Tax Provision |
|---|---|---|
| Portable Electronics & Tools | 5-Year Property | 40% Bonus Depreciation |
| Section 179 Equipment | Immediate Expensing | $1,220,000 Annual Limit |
| Vehicle Accessories | 5-Year Property | Half-Year Convention |
MACRS Recovery Periods and Convention Rules
IRS guidelines classify portable مكانس كهربائية, air pumps, and car fridges as 5-year property under the Modified Accelerated Cost Recovery System. Businesses calculate annual deductions by applying the half-year convention, which treats the asset as if it entered service on July 1st regardless of the actual purchase date. If a company acquires more than 40% of its total annual assets during the final three months of the fiscal year, the mid-quarter convention replaces the half-year rule to adjust the timing of the tax recovery.
The double declining balance method allows owners to accelerate deductions during the early years of the asset’s life. Taxpayers switch to the straight-line method only when the resulting annual allowance becomes higher than the declining balance figure. To establish the depreciable basis for all accessories, the owner must first subtract the estimated salvage value from the original purchase price. This ensures the total depreciation over the five-year period aligns with the actual cost incurred by the business.

Section 179 Expensing and 2026 Bonus Allowances
Section 179 provides an immediate tax benefit by allowing businesses to deduct the full purchase price of qualifying equipment in the year of acquisition. This provision applies up to a $1,220,000 annual limit for the 2026 tax year. For property that exceeds these limits or does not qualify for full expensing, the 40% bonus depreciation allowance provides an additional layer of tax relief. This allowance applies to qualified assets placed in service throughout 2026, significantly reducing the taxable income for that reporting period.
Tracking the adjusted basis is essential for managing the long-term tax impact of these assets. Owners calculate this figure by subtracting all accumulated depreciation from the initial purchase cost. During a resale or liquidation event, the difference between the sale price and the adjusted basis determines the taxable gain or loss. Under GASB #34 standards, assets must possess a useful life of at least one reporting period to qualify for capitalization and subsequent depreciation schedules.
The “Scrap Value” of Copper Motors vs. Plastic/Lithium
Copper motors retain high scrap value because they contain 10% to 18% high-grade copper windings. While lithium batteries scrap for only $0.10 to $0.30 per pound, processed copper fetches up to $4.50 per pound. This makes copper-based tools significantly more valuable at the end of their lifecycle compared to units with integrated batteries or plastic housings.
Copper Concentration and Material Density in Electric Motors
DC motors used in high-performance accessories contain 15% to 18% copper windings by weight. This concentration defines the core material value, as fractional electric motors generally yield between 9% and 10% copper. The remaining 90% of the unit consists of low-value steel, which provides the structural weight but offers minimal financial return compared to the internal wiring.
General electric motors average $0.19 per pound when sold as-is at recycling centers. This price reflects the standard blend of copper and high steel content found in industrial and consumer units. Motor units with plastic-heavy casings or aluminum windings fall into the Copper Bearing Material (CBM) category. These units command lower market rates because they require more intensive processing to separate the metallic content from non-recyclable debris.
Scrap Yield and Market Pricing for Recycled Components
Clean #1 copper wire or tubing reaches prices between $3.30 and $4.50 per pound according to 2026 market assessments. Manual disassembly of small motors often doubles the scrap value, increasing returns from a baseline of $26.70 to approximately $53.92 through material separation. This value increase rewards the labor required to strip copper windings away from the steel frame and electronic housing.
Lithium batteries offer a minimal recovery rate, typically fetching only $0.10 to $0.30 per pound at scrap yards. Steel components from motor frames contribute a baseline value of approximately $0.10 per pound to the total recovery calculation. Copper-based tools outperform battery-integrated units because they provide a high density of high-demand metal, whereas lithium and plastic components yield negligible returns at the end of their service life.
Maximizing ROI at End-of-Life
Businesses maximize ROI by applying rigorous valuation models—sales comparison, cost, or income approaches—to time the sale of assets before they reach forced liquidation value (FLV). Tracking equipment over an 84-month period reveals a standard 25% first-year drop followed by 10% annual depreciation, stabilizing at 40% residual value.
| Lifecycle Milestone | Residual Value (FMV) | Valuation Logic |
|---|---|---|
| Year 1 | 75% | Initial 25% depreciation from new purchase price. |
| Year 4 | 52% | Standard 15% annual reduction model over 4 years. |
| السنة السادسة (84 شهرًا) | 40% | القيمة المتبقية لآلات التصنيع الوظيفية. |
أطر تقييم أصول الاسترداد
يتطلب تحديد سعر السوق للمعدات المستعملة مزيجًا من ثلاثة منهجيات رئيسية. تعتمد طريقة مقارنة المبيعات على بيانات السوق الحالية الناتجة عن معاملات أصول مماثلة لتأسيس معيار مرجعي، مع إجراء تعديلات وفقاً للحالة والอายุ المحددين للآلة. توفر هذه الطريقة أكثر صور الدقة انعكاساً للسعر الذي يستعد المشتري المدرك لدفعه في سوق مفتوحة.
تركز طريقة التكلفة على حساب تكلفة استبدال الأصل الحالية وطرح إهلاكه المادي المتراكم. وتُعد هذه الطريقة فعّالة للآلات المتخصصة حيث تكون أسواق إعادة البيع النشطة محدودة. بالإضافة إلى ذلك، تقيّم طريقة الدخل القيمة بناءً على القدرة على توليد الإيرادات من الأصل إذا ظل قيد الاستخدام. وفيما يخص الآلات الوظيفية، غالباً ما تتضمن القيمة العادلة للسوق (FMV) تكاليف التثبيت والتجميع، ما يُضيف علاوة فوق الوحدات غير المثبتة.
منحنيات الإهلاك وتوقيت التصفية
يتضمن التنبؤ بالقيمة المتبقية نموذج إهلاك قياسي تفقد فيه المعدات 25% من قيمتها في العام الأول، تليه نسب انخفاض سنوية تبلغ 10%. وباستخدام صيغة القيمة المعاد بيعها = السعر الأصلي × (1 – معدل الإهلاك)^السنوات، يمكن للمديرين توقع استرداد رأس المال في أي نقطة خلال دورة حياة الأصل. فعلى سبيل المثال، تحتفظ آلة تبلغ قيمتها 260,000 دولار تقريباً بـ 100,000 دولار بعد ست سنوات من التشغيل.
يُعد توقيت الخروج العامل الأهم لتحقيق أقصى عائد على الاستثمار. يساعد مراقبة القيمة المتبقية خلال دورة مدتها 84 شهراً (7 سنوات) المالكين على تجنب الخسائر الحادة المرتبطة بالقيمة الصافية للتصفية الإجبارية (FLV). في حين تفترض القيمة العادلة للسوق بيعاً منظماً يتوفر له وقت معقول للتعرض في السوق، تمثل القيمة الصافية للتصفية الإجبارية العوائد الإجمالية الناتجة عن مزاد فوري. ويضمن الحفاظ على حالة المعدة التي تدعم “القيمة العادلة للسوق للمثبت” تحقيق أعلى قدر ممكن من الاستبقاء لرأس المال الأصلي أثناء التصفية.
خاتمة
تتطلب إدارة دورة حياة معدات التنظيف التجارية فهماً واضحاً لكيفية شيخوخة التقنيات المختلفة. ورغم أن الأجهزة الإلكترونية الذكية والوحدات المعتمدة على البطاريات توفر راحة عصرية، فإن فقدان قيمتها السريع يفاجئ غالباً المالكين الذين يتوقعون احتفاظاً طويل الأمد. ويوفر اختيار الآلات ذات الأسلاك أو الأدوات الميكانيكية أرضية مالية أكثر استقراراً، نظراً لأن هذه الأصول تستفيد من أسعار النحاس المرتفعة في الخردة والطلب المنتظم على المعدات الصناعية المُجددة. وتحصل الشركات التي تتعقّب هذه الأدوات عبر طرق محاسبية محددة مثل خصم وتسارع المخصصات المعجلة (MACRS) على صورة أدق لإمكانات الاسترداد قبل سنوات عديدة من وصول المعدات إلى حد خدمتها النهائي.
يعتمد النجاح في السوق الثانوية لعام 2026 على الصيانة الموثقة والتوقيت الاستراتيجي. ويتيح بيع الأصول قبل وصولها إلى حالة التصفية الإجبارية لشركات التنظيف من捕获 أعلى العوائد الممكنة بدلاً من الرضا بأسعار أرضية المزادات. ومن خلال التركيز على القيمة المادية الجوهرية للنحاس ومعايير السلامة الخاصة بالمكونات المُعاد تجهيزها، يحول المديرون المخزون القديم إلى مصدر متوقع للنقد. ويمزج هذا الأسلوب بين التكلفة الأولية العالية للشراء وخطة خروج واقعية تحمي الصحة المالية للشركة.
الأسئلة المتداولة
هل تحتفظ مكانس الغبار التجارية والصناعية بقيمتها في إعادة البيع؟
تحافظ الطرازات الصناعية على قيمة معتدلة بفضل توقع معدل نمو سنوي مركب يبلغ 4.3% حتى عام 2035. وفي سوق 2026 الثانوية،عادةً ما يتم إعادة بيع الوحدات التجارية بحالة جيدة بنحو 50-70% من تكلفتها الأصلية، وذلك وفقاً لجدول إهلاك قياسي يترك قيمة متبقية بنسبة 20% بعد سبع سنوات.
هل يستحق الشراء مكانس غبار لاسلكية مستعملة؟
ينطوي شراء الطرازات اللاسلكية المستعملة على مخاطر أعلى، لأن بطاريات الليثيوم أيون عادةً ما يكون عمرها الفعال من سنتين إلى ثلاث سنوات فقط. وتفقد هذه الوحدات قيمتها بسرعة أكبر بكثير من البدائل ذات الأسلاك، التي تعتمد على محركات نحاسية طويلة الأمد بدلاً من خلايا الطاقة المستهلكة.
What is the scrap value of a non-functional vacuum cleaner?
Scrap value for مكانس كهربائية remains low, typically ranging from $0.10 to $0.50 per pound. The primary value resides in the copper found within the motor windings, while the plastic housing and filtration components offer negligible returns at recycling centers.
How do cleaning equipment depreciation schedules affect business taxes?
Most cleaning equipment follows a straight-line depreciation model over five to seven years. For 2026 tax filings, commercial entities often write down these assets to a 20% residual value, though portable electronics may require accelerated schedules due to faster technological obsolescence.
 English
 Español
 Français
 Deutsch
 Português do Brasil
 Русский
 한국어
 日本語
 العربية