


Muchas empresas de limpieza comercial pasan por alto cómo la depreciación de activos erosiona su margen hasta que intentan vender hardware usado. Distinguir entre activos electrónicos de alta tecnología y herramientas mecánicas tradicionales ayuda a los propietarios a proyectar los retornos reales de efectivo y a gestionar mejor los listados en el mercado secundario.
Desglosamos los marcos de valoración de 2026 para aspiradoras comerciales, comparando los pisos de liquidación entre modelos con cable y inalámbricos. Esta guía explora por qué los motores de cobre retienen un valor de chatarra de hasta 4,50 dólares por libra, mientras que las unidades alimentadas por baterías suelen enfrentar una penalización de precio del 50 % en solo tres años de servicio.
La curva de depreciación: electrónica frente a herramientas
Electronics shed 30–70% of their value in the first year due to rapid technological obsolescence, while traditional tools follow a more stable 16% annual depreciation rate. Managing these assets requires distinct accounting methods—declining balance for tech and straight-line for tools—to accurately project resale returns in 2026.
Technological Obsolescence and Early-Year Value Loss
Laptops and smart electronics lose 30–70% of their initial purchase price within the first 12 months. This sharp decline stems from rapid advancements in processing power and battery efficiency that render older models functionally obsolete, even if they remain in perfect physical condition. Portable devices like vacuum controllers and smart car fridges often see value drops of £240 on a £600 investment by the second year. While physical wear matters, the market saturation of newer, more efficient 2026 hardware releases exerts the strongest downward pressure on resale prices.
Comparative Depreciation Rates and Accounting Methods
Mechanical tools follow a more predictable path, sustaining a 16% annual depreciation rate across a standard 8-year useful life. Financial managers use the declining balance method to track high-tech devaluation, applying a 40% rate to the remaining book value each year to reflect real-world market pricing. Desktop computers and stationary equipment maintain a maximum official depreciation rate of 26% per year over a 3-to-10-year span. Applying the double declining balance method helps organizations match their books to the 2026 market, as it doubles the 20% straight-line rate to 40% for IT assets.

El estigma de la “batería usada” en el mercado de segunda mano
Buyers often penalize used battery-powered assets with a 50% value drop over three years, despite technical data showing only 1-2% annual degradation. This stigma persists due to a lack of standardized diagnostic benchmarks, making the battery a high-risk ‘black box’ for second-hand participants.
Information Asymmetry and Asset Valuation Gaps
Traditional automotive markets rely on a century of odometer-based pricing to gauge residual value. Lithium-ion systems currently lack these established historical benchmarks, leaving buyers without a reliable metric for long-term health. Since the paquete de baterías constitutes the majority of the asset’s total cost, any uncertainty regarding its condition translates into an aggressive price penalty. Statistics show that 3-year-old electric units often lose more than half their original price, while mechanical alternatives retain roughly 61% of their value. This discrepancy stems from an information gap rather than actual physical wear or mechanical failure.
Technical Degradation Metrics and Market Recovery
Technical evidence suggests that post-2016 battery systems are far more durable than consumer sentiment implies. Most units experience only 1% to 2% annual capacity loss, and only 1% of EVs produced after 2016 have required a full battery replacement. Market participants are closing the trust gap by adopting smart diagnostics and clear warranty transfer protocols. Certified units move through the secondary market six times faster than those without documented health reports. The projected $4.2 billion second-life battery market by 2035 further stabilizes residual values by ensuring that even aged units remain valuable for grid storage and recycling applications.
Potencial de reacondicionamiento: valor de reventa de modelos con cable
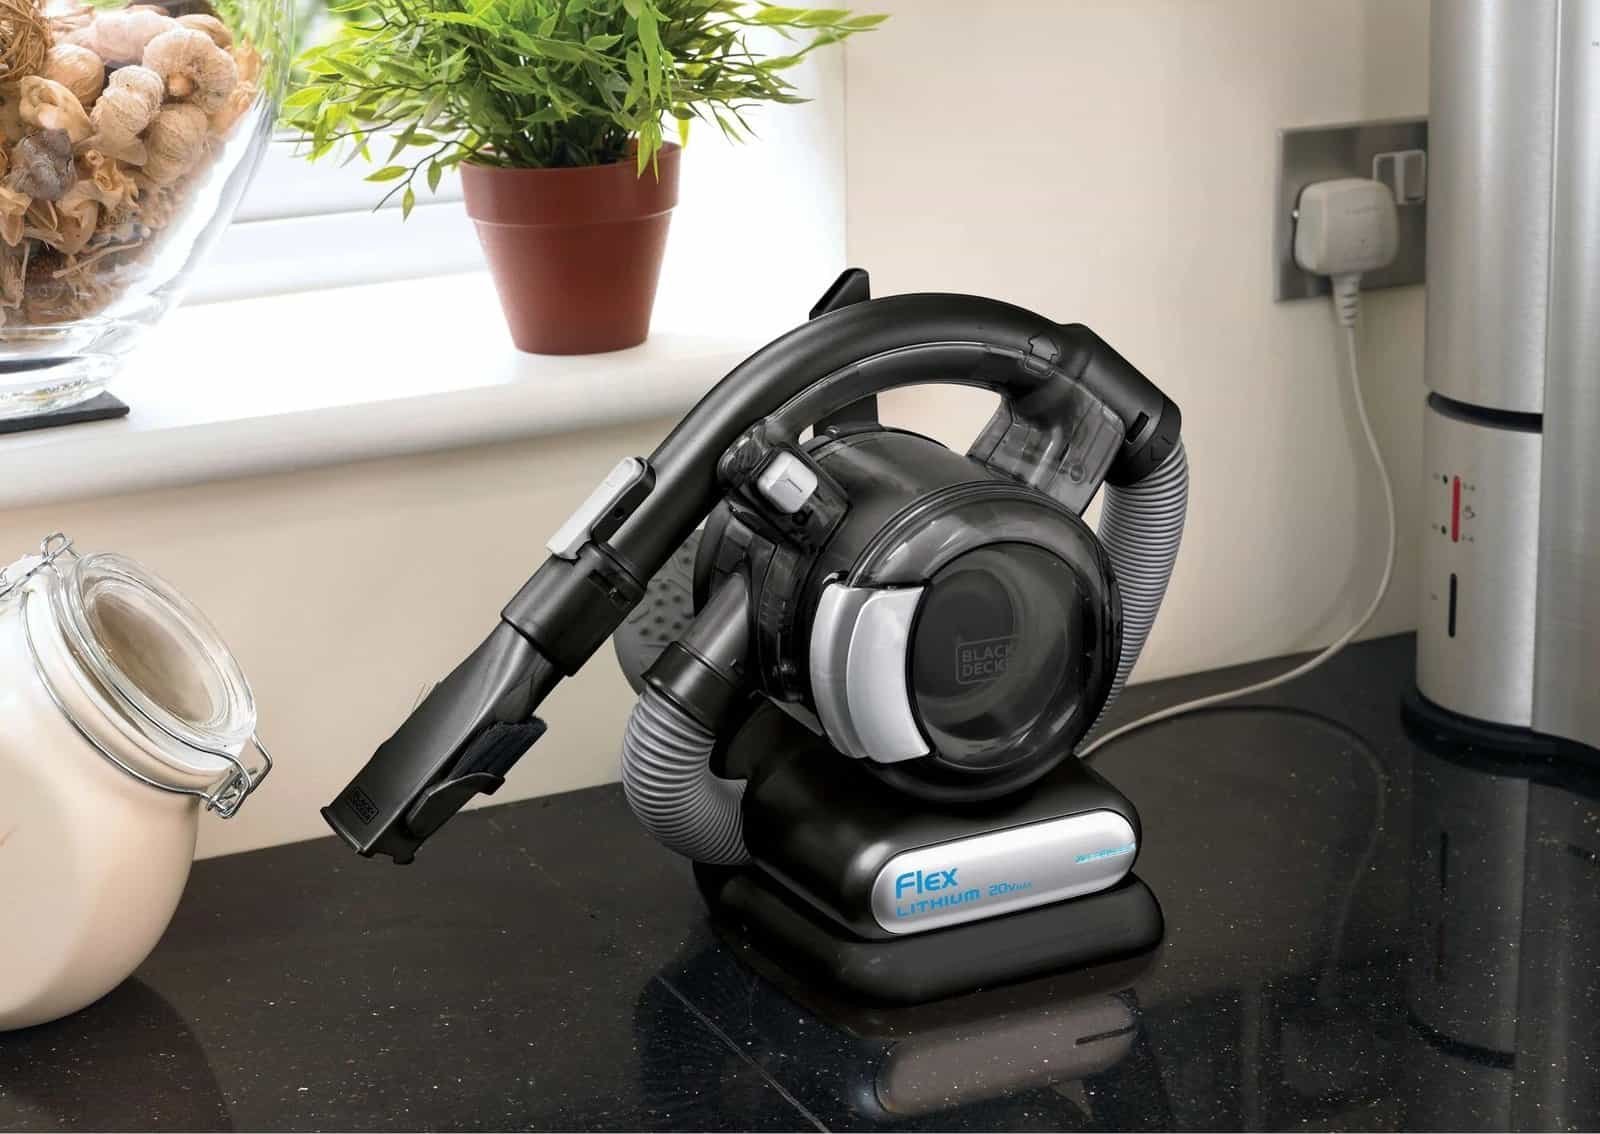
Corded equipment consistently maintains higher resale value than cordless alternatives in 2026, often retaining 70% of its original list price. This stability results from the durability of copper motors and strict adherence to NEC 2020 reconditioning standards, which ensure safety and performance without the risks of battery degradation.
Value Retention and the Corded Advantage
Secondary market buyers prioritize corded tools to avoid the stigma associated with used batteries and the unpredictable costs of cell replacement. Because corded motors lack volatile chemical components, they offer a predictable service life that appeals to B2B liquidation cycles. Refurbished industrial electrical gear offers 40-60% savings compared to new units, which sustains a high demand for used equipment in the secondary market.
Valuation models for 2026 typically set a baseline of 70% of the original list price for name-brand corded tools accompanied by documented maintenance logs. This high retention rate stems from the inherent longevity of copper-wound motors and the absence of proprietary battery platforms that often lead to obsolescence. Asset managers rely on these stable valuations to justify the procurement of corded equipment for long-term industrial projects.
Regulatory Standards for Reconditioned Equipment
NEC 2020 sections 240.88 and 408.8(B) establish the legal framework for reconditioning circuit breakers and switchgear. These regulations allow components like molded-case circuit breakers and medium-voltage power circuit breakers to be restored to operating condition while maintaining their market value. Field-labeling for reconditioned switchboards permits commercial entities to liquidate assets safely, provided they follow local electrical codes and performance testing requirements.
Compliance with the NEMA CS 100-2020 standard ensures that reconditioned assets meet rigorous safety and labeling criteria. This standard provides the prescriptive actions necessary to verify that used equipment performs as intended after refurbishment. Restrictions under NEC 240.88(B)(1) prohibit the reconditioning of electronic trip units on low-voltage breakers, which sets a hard ceiling on the resale potential of more complex electronic components compared to standard electromechanical corded machinery.
Escala tu marca con fabricación de aspiradoras de alto rendimiento

Valor de liquidación para empresas de limpieza comercial
Liquidation value represents the estimated net cash a cleaning business generates by selling assets and settling debts in a short timeframe. In 2026, this value serves as a safety floor, typically recovery 50% of inventory book value and 70% of accounts receivable, while specialized equipment fluctuates based on secondary market demand.
Valuation Frameworks and Asset Recovery Floors
Calculating a cleaning company’s base value requires a clear distinction between orderly and forced liquidation. An orderly liquidation assumes the business has several months to identify buyers for specialized equipment and vehicles, which generally secures higher recovery rates. Forced liquidation assumes a rapid exit, often at auction, where assets sell quickly at a steep discount to their book value.
Standard market assessments in 2026 weigh the relationship between EBITDA multiples and the hard asset floor. While healthy operations might trade at 3x to 5x EBITDA, the liquidation value establishes the absolute minimum price for an exit. When a business experiences financial distress, this floor ensures that creditors and owners understand the cash-in-hand reality of the company’s tangible assets.
Owner dependence and customer concentration significantly influence the final recovery. If a cleaning service relies heavily on the owner’s personal relationships or a single large contract, the intangible value disappears during a sale. In these scenarios, the valuation shifts focus entirely to physical inventory and the strength of the accounts receivable aging report.
Technical Recovery Benchmarks for Equipment and Receivables
Inventory recovery rates for cleaning supplies and chemicals average approximately 50 cents on the dollar. This discount reflects the logistical challenges of transporting bulk chemicals and the limited demand for partially used stock. High-quality, sealed concentrates from reputable brands maintain the best recovery percentages in the secondary market.
Liquidation discounting for accounts receivable often reaches 30%, meaning buyers pay roughly 70% of the book value. This reduction accounts for the increased difficulty of collecting payments once a service provider ceases operations. Clients sometimes delay final payments during business transitions, making a verifiable and current AR report vital for a successful asset sale.
Resale performance for specialized hardware like HEPA-filtered vacuums and industrial floor scrubbers remains steady in the second-hand facility management market. These items hold value better than generic janitorial tools because of their high replacement costs and especificaciones técnicas. Maintaining detailed maintenance logs for this equipment helps support higher recovery values during the liquidation process.
Implicaciones fiscales: planes de depreciación de activos fijos
Businesses recover the cost of automotive accessories like portable fridges and Los cargadores para vehículos eléctricos through the Modified Accelerated Cost Recovery System (MACRS). For the 2026 tax year, these assets typically fall under the 5-year property class, allowing owners to apply Section 179 deductions and bonus depreciation to front-load expenses and lower the adjusted basis before liquidation.
| Asset Category | Recovery Period | 2026 Tax Provision |
|---|---|---|
| Portable Electronics & Tools | 5-Year Property | 40% Bonus Depreciation |
| Section 179 Equipment | Immediate Expensing | $1,220,000 Annual Limit |
| Vehicle Accessories | 5-Year Property | Half-Year Convention |
MACRS Recovery Periods and Convention Rules
IRS guidelines classify portable aspiradoras, air pumps, and car fridges as 5-year property under the Modified Accelerated Cost Recovery System. Businesses calculate annual deductions by applying the half-year convention, which treats the asset as if it entered service on July 1st regardless of the actual purchase date. If a company acquires more than 40% of its total annual assets during the final three months of the fiscal year, the mid-quarter convention replaces the half-year rule to adjust the timing of the tax recovery.
The double declining balance method allows owners to accelerate deductions during the early years of the asset’s life. Taxpayers switch to the straight-line method only when the resulting annual allowance becomes higher than the declining balance figure. To establish the depreciable basis for all accessories, the owner must first subtract the estimated salvage value from the original purchase price. This ensures the total depreciation over the five-year period aligns with the actual cost incurred by the business.

Section 179 Expensing and 2026 Bonus Allowances
Section 179 provides an immediate tax benefit by allowing businesses to deduct the full purchase price of qualifying equipment in the year of acquisition. This provision applies up to a $1,220,000 annual limit for the 2026 tax year. For property that exceeds these limits or does not qualify for full expensing, the 40% bonus depreciation allowance provides an additional layer of tax relief. This allowance applies to qualified assets placed in service throughout 2026, significantly reducing the taxable income for that reporting period.
Tracking the adjusted basis is essential for managing the long-term tax impact of these assets. Owners calculate this figure by subtracting all accumulated depreciation from the initial purchase cost. During a resale or liquidation event, the difference between the sale price and the adjusted basis determines the taxable gain or loss. Under GASB #34 standards, assets must possess a useful life of at least one reporting period to qualify for capitalization and subsequent depreciation schedules.
El “valor de chatarra” de los motores de cobre frente al plástico/litio
Copper motors retain high scrap value because they contain 10% to 18% high-grade copper windings. While lithium batteries scrap for only $0.10 to $0.30 per pound, processed copper fetches up to $4.50 per pound. This makes copper-based tools significantly more valuable at the end of their lifecycle compared to units with integrated batteries or plastic housings.
Concentración de cobre y densidad del material en motores eléctricos
Los motores DC utilizados en accesorios de alto rendimiento contienen entre un 15 % y un 18 % de devanados de cobre por peso. Esta concentración define el valor del material, ya que los motores eléctricos fraccionarios suelen generar entre un 9 % y un 10 % de cobre. El 90 % restante de la unidad está compuesto por acero de bajo valor, que aporta el peso estructural pero ofrece un retorno financiero mínimo en comparación con el cableado interno.
Los motores eléctricos en general tienen un precio promedio de $0.19 por libra cuando se venden en su estado actual en centros de reciclaje. Este precio refleja la combinación estándar de cobre y alto contenido de acero propia de las unidades industriales y de consumo. Las unidades de motor con carcasas predominantemente plásticas o devanados de aluminio se clasifican como material con borne de cobre (CBM). Estas unidades obtienen tasas de mercado más bajas porque requieren un procesamiento más intensivo para separar el contenido metálico de los residuos no reciclables.
Producción y precios de mercado de componentes reciclados
El cable o tubo de cobre limpio alcanza precios entre $3.30 y $4.50 por libra según evaluaciones del mercado de 2026. La desensamblaje manual de motores pequeños suele duplicar el valor del chatarra, incrementando los rendimientos desde una línea base de $26.70 hasta aproximadamente $53.92 mediante la separación de materiales. Este aumento de valor recompensa la mano de obra necesaria para pelar los devanados de cobre del marco de acero y la carcasa electrónica.
Las baterías de litio ofrecen una tasa de recuperación mínima, generalmente obteniendo solo $0.10 a $0.30 por libra en chatarrerías. Los componentes de acero de los marcos de los motores contribuyen con un valor base de aproximadamente $0.10 por libra al cálculo total de recuperación. Las herramientas con base de cobre superan a las unidades con batería integrada, ya que proporcionan una alta densidad de metal de alta demanda, mientras que los componentes de litio y plástico ofrecen rendimientos insignificantes al final de su vida útil.
Maximización del ROI al final de la vida útil
Las empresas maximizan el ROI aplicando modelos de valoración rigurosos, como comparación de ventas, costo o ingreso, para sincronizar la venta de activos antes de que alcancen su valor de liquidación forzosa (FLV). El seguimiento del equipo durante un período de 84 meses revela una caída estándar del 25 % en el primer año, seguida de una depreciación anual del 10 %, estabilizándose en un valor residual del 40 %.
| Hito del ciclo de vida | Valor residual (FMV) | Lógica de valoración |
|---|---|---|
| Año 1 | 75% | Depreciación inicial del 25 % sobre el precio de compra nuevo. |
| Año 4 | 52% | Modelo estándar de reducción anual del 15 % durante 4 años. |
| Year 6 (84-Month) | 40% | Residual floor for functional machine tools. |
Valuation Frameworks for Asset Recovery
Determining the market price of used equipment requires a blend of three primary methodologies. The sales comparison approach uses current market data from similar asset transactions to establish a benchmark, adjusting for the specific condition and age of the machinery. This method provides the most accurate reflection of what a willing buyer will pay in an open market.
The cost approach focuses on calculating the current replacement cost of the asset and subtracting accumulated physical depreciation. This is effective for specialized machinery where active resale markets are limited. Additionally, the income approach assesses value based on the revenue-generating potential of the asset if it remains in use. For functional machinery, the Fair Market Value (FMV) often includes installation and assembly costs, which adds a premium over uninstalled units.
Depreciation Curves and Liquidation Timing
Predicting residual value involves a standardized depreciation model where equipment loses 25% of its value in the first year, followed by a 10% annual decline. Using the formula Resale Value = Original Price × (1 – Depreciation Rate)^Years allows managers to project capital recovery at any point in the lifecycle. For example, a $260,000 machine typically retains approximately $100,000 in value after six years of operation.
Timing the exit is the most critical factor in maximizing ROI. Monitoring residual value over an 84-month (7-year) cycle helps owners avoid the steep losses associated with Forced Liquidation Value (FLV). While Fair Market Value assumes an orderly sale with reasonable exposure time, FLV represents the gross proceeds from an immediate auction. Maintaining the equipment to support an “installed FMV” status ensures the highest possible retention of original capital during liquidation.
Reflexiones finales
Managing the lifecycle of commercial cleaning equipment requires a clear understanding of how different technologies age. While smart electronics and battery-powered units offer modern convenience, their rapid value loss often surprises owners who expect long-term retention. Choosing corded machinery or mechanical tools provides a more stable financial floor, as these assets benefit from high copper scrap prices and steady demand for refurbished industrial gear. Businesses that track these tools through specific accounting methods like MACRS gain a more accurate view of their recovery potential well before the equipment reaches its service limit.
Success in the 2026 secondary market depends on documented maintenance and strategic timing. Selling assets before they reach a forced liquidation state allows cleaning companies to capture the highest possible returns instead of settling for auction-floor prices. By focusing on the intrinsic material value of copper and the safety standards of reconditioned components, managers turn old inventory into a predictable source of cash. This strategy balances the high initial cost of procurement with a realistic exit plan that protects the company’s financial health.
Preguntas frecuentes
Do commercial and industrial vacuum cleaners hold their resale value?
Industrial models maintain moderate value due to a projected 4.3% CAGR through 2035. In the 2026 secondary market, well-maintained commercial units typically resell for 50-70% of their original cost, following a standard depreciation schedule that leaves a 20% residual value after seven years.
Is it worth purchasing a used cordless vacuum cleaner?
Purchasing used cordless models involves higher risk because lithium-ion batteries typically have an effective lifespan of only two to three years. These units depreciate significantly faster than corded alternatives, which rely on long-lasting copper motors rather than consumable power cells.
What is the scrap value of a non-functional vacuum cleaner?
Scrap value for aspiradoras remains low, typically ranging from $0.10 to $0.50 per pound. The primary value resides in the copper found within the motor windings, while the plastic housing and filtration components offer negligible returns at recycling centers.
How do cleaning equipment depreciation schedules affect business taxes?
Most cleaning equipment follows a straight-line depreciation model over five to seven years. For 2026 tax filings, commercial entities often write down these assets to a 20% residual value, though portable electronics may require accelerated schedules due to faster technological obsolescence.
 English
 Español
 Français
 Deutsch
 Português do Brasil
 Русский
 한국어
 日本語
 العربية